
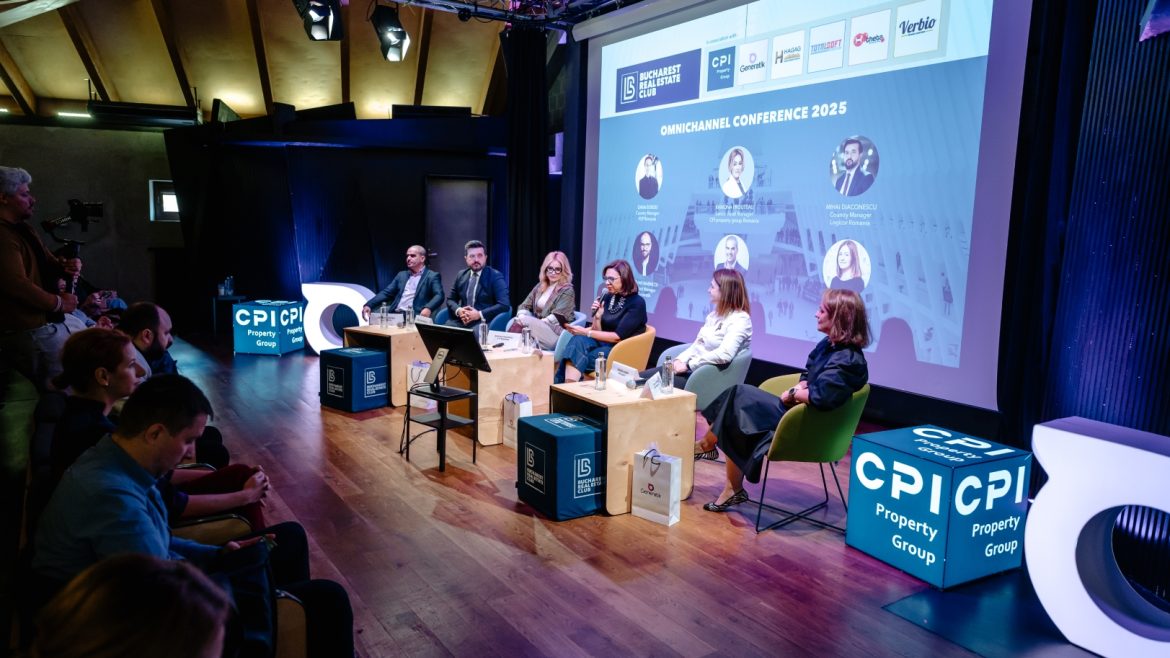
Retail and logistics deliveries totalled 339,600 sqm in the first three quarters of 2025, according to data presented by iO Partners during the Omnichannel Conference held in Bucharest.
In the retail market, total deliveries reached 148,000 sqm in the first nine months. The largest projects were Mall Moldova in Iași (62,000 sqm, extension), Agora Mall in Arad (36,000 sqm, reopening after renovation), and Iulius Mall Suceava (14,500 sqm, extension).
Romania continues to attract new international brands in fashion, sports, and fast food, despite a period of cautious consumer spending. Recent market entries include Wendy’s, Funky Buddha, Sports Direct, and Action.
The retail portfolio of CPI Romania, comprising 250,000 sqm across Bucharest, Constanța, Cluj-Napoca, Pitești, Baia Mare, Iași, and Botoșani, continues to perform strongly with an occupancy rate of 98%. This result reflects the owner’s strategic investments in modernizing the shopping centres and attracting leading international brands. In September, Primark opened a new 5,000 sqm store at VIVO! Cluj-Napoca, with a 3,700 sqm retail area spread over two floors.
In Bucharest, Calea Victoriei has become over the years the city’s luxury retail hotspot, home to brands such as Louis Vuitton, Hugo Boss, and Max Mara. A milestone for the area’s development will be the opening of H Știrbei Palace, owned by Hagag Development Europe, scheduled for the end of this year. The investor will launch Romania’s first department store, featuring collections from Dior, Saint Laurent, Valentino Garavani, Celine, Loewe, Dolce & Gabbana, Santoni, Roger Vivier, Amina Muaddi, Rene Caovilla, Jimmy Choo, Moncler, and other prestigious brands.
Prime retail rents are on an upward trend, driven by strong demand and low vacancy rates. In Bucharest, rents have reached €85/sqm/month, while in Cluj-Napoca, Timișoara, and Iași, they range between €55–65/sqm/month. The stock of modern retail spaces currently stands at 1,253,000 sqm in Bucharest, 240,000 sqm in Timișoara, 237,000 sqm in Iași, and 158,000 sqm in Cluj-Napoca.
In the logistics and industrial parks sector, total deliveries reached 191,600 sqm in the first nine months of the year. The Top 10 leasing transactions accounted for 284,800 sqm, with 41% of tenants coming from the retail and consumer goods industries.
VGP’s Romanian portfolio has surpassed 420,000 sqm of gross lettable area this year, with properties in Bucharest, Brașov, Sibiu, Timișoara, and Arad. One of the year’s highlights was the opening of VAT Group’s global production center in Arad—the company’s third facility worldwide, after Switzerland and Malaysia. VGP currently has 160,000 sqm under development, scheduled for completion in Q1 2026, when the Romanian portfolio will exceed 600,000 sqm.
Logicor is a leading owner, manager, and developer of European logistics real estate. Its portfolio spans over 19 million sqm of warehouse space in key transportation hubs and near major population centres, supporting over 2,200 customers. The company’s strategy focuses on expanding its presence in high-demand and strategic European markets. In Romania, this means a continued emphasis on Bucharest, where it holds the largest footprint, with over 250,000 sqm of a total portfolio exceeding 330,000 sqm of Class A warehouse space. The total value of its current portfolio in Romania exceeds EUR 220 million.

